 Read time 8 min
✓
✓
✓
✓
✓
For real estate investors, CAM reconciliation isn’t just a tenant billing exercise but a direct input into recoverable income, Net Operating Income, and asset valuation. Getting reimbursement calculations right protects NOI; getting them wrong shows up as revenue leakage that compounds across a portfolio and surfaces again at acquisition diligence.
CAM reconciliation is the process of comparing a property’s actual common area maintenance expenses against the amounts allocated and recovered from tenants under their lease agreements. For real estate investors, the process goes beyond calculating tenant charges — it can reveal recovery gaps, expense discrepancies, and direct impacts on property-level performance. This article focuses on what the process means for your returns. If you’re looking for the operational steps involved, see our guide to the CAM reconciliation process.
Why CAM Reconciliation Matters to Real Estate Investors
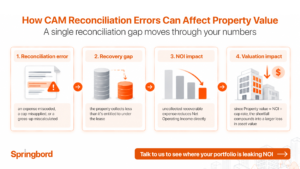
CAM reconciliation matters to real estate investors because it directly affects four areas: NOI, expense recovery, revenue leakage, and portfolio performance.
- NOI — recoverable expenses that go uncollected reduce NOI directly, and since commercial property value is generally derived from NOI, that impact doesn’t stay contained to a single line item on a statement.
- Expense recovery — the recovery ratio (recovered vs. total CAM cost) signals how much operating risk you’re actually retaining versus passing through to tenants. A landlord consistently recovering only a portion of eligible CAM costs is absorbing operating risk that the lease may have been structured to pass through to tenants.
- Leakage — small, recurring reconciliation errors compound quietly across a portfolio, unlike a single large loss that gets flagged and fixed immediately. For example, a $2,000 reconciliation error repeated across 40 leases would represent an $80,000 recovery gap before considering any related effects on NOI.
- Portfolio oversight — inconsistent reconciliation practices across properties make it harder to benchmark performance, spot underperforming assets, or trust the NOI figures rolling up into investor reporting.
Calculating CAM Reimbursement
What Is CAM Reimbursement?
CAM reimbursement is the amount a tenant owes (or is owed) after actual common area expenses are reconciled against the estimated monthly payments billed over the year.
What Goes Into a CAM Reimbursement Calculation?
A reimbursement calculation typically factors in the:
- tenant’s pro-rata share
- recoverable operating expenses
- lease-specific caps
- expense exclusions
- gross-up provisions
- applicable base-year provisions
CAM Reimbursement Calculation Example
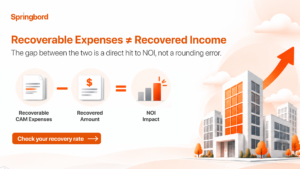
If a property’s total recoverable CAM expenses for the year are $500,000. Assuming the lease allocates 5% of recoverable expenses to the tenant, their pro-rata share is $25,000. If that tenant paid $22,000 in estimated monthly CAM charges over the year, they owe an additional $3,000 at reconciliation. Multiply small variances like this across dozens of tenants, and the aggregate swing in recovered income becomes significant.
How CAM Reimbursement Affects NOI & Property-Level Performance
Underbilled reimbursements mean the property absorbs costs it should have recovered, making it a direct drag on Net Operating Income. Since commercial property value is typically calculated by dividing NOI by the market cap rate, even a modest, uncorrected expense gap can compound into a measurable valuation impact.
The link between reconciliation accuracy and Net Operating Income runs both directions: poor reconciliation understates recoverable income, while overly aggressive billing creates disputes that eventually cost more in concessions and turnover than the extra recovery was worth. The goal isn’t maximizing what’s billed — it’s accurately collecting what the lease actually entitles you to.
CAM Reconciliation for REITs and Large Commercial Property Portfolios
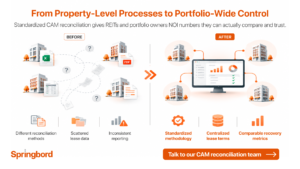
For REITs and institutional owners managing dozens or hundreds of leases, CAM reconciliation stops being a single-property task and becomes a portfolio-wide control function. Inconsistent categorization or reconciliation timing across properties makes it difficult to compare asset performance or roll figures up for investor and board reporting with confidence. This gets harder as portfolios grow through acquisition, since newly acquired properties often arrive with their own reconciliation habits, spreadsheet formats, and expense-coding conventions that don’t match the rest of the portfolio.
Standardized reconciliation practices (the same categorization rules, review cadence, variance thresholds, and documentation standard applied across every property) make portfolio-level NOI reporting far more reliable and make it possible to spot which specific assets are underperforming on recovery rather than assuming portfolio averages tell the full story.
How CAM Reconciliation Helps Identify Revenue Leakage
Revenue leakage in CAM reconciliation rarely shows up as one obvious error. CAM revenue leakage occurs when recoverable expenses are not fully billed or collected because of incorrect expense classification, lease-term application, allocation, caps, gross-ups, or missing supporting data.
It’s usually a pattern: a recoverable expense category consistently miscoded as non-recoverable, a cap misapplied across multiple leases with similar terms, or a gross-up calculation quietly wrong for a subset of tenants because occupancy data wasn’t updated. None of these individually looks alarming on a single statement. They only become visible when someone compares reconciliation outcomes across tenants or across years and notices the same type of gap recurring.
A disciplined reconciliation process, one built to catch common CAM reconciliation challenges before they repeat, is what turns leakage from a recurring loss into a one-time fix. The distinction matters for underwriting too: a leakage pattern identified and corrected raises forward NOI expectations, while one left undetected keeps quietly understating what the asset can actually produce.
CAM Reconciliation During Acquisition Due Diligence
Reconciliation history is a diligence item, not just an accounting record. Buyers typically review several years of CAM reconciliation statements before closing. They’re checking for unrecovered expenses, unresolved tenant disputes, or inconsistent categorization.
These issues can distort the seller’s reported NOI and make it harder for a buyer to determine the property’s sustainable operating performance. A pattern of under-billed CAM charges is a good example. It usually means the property was managed loosely, not that recovery has hit a hard ceiling. That cuts both ways for a buyer: it’s a real opportunity to improve recovery after closing, but it also means the in-place NOI used to justify the purchase price wasn’t fully real.
Clean, well-documented reconciliation history (clear supporting statements, a consistent methodology year over year, and a low rate of tenant disputes) supports a smoother diligence process and a valuation that holds up under scrutiny from lenders and co-investors alike.
During acquisition due diligence, investors should examine:
- historical CAM reconciliation statements
- recoverable vs. non-recoverable expense classifications
- tenant recovery rates
- caps and exclusions
- gross-up methodology
- unresolved tenant disputes
- reconciliation timing
- recurring recovery shortfalls
Common CAM Reconciliation Problems Investors Should Watch For
A few patterns show up repeatedly across portfolios: expenses billed to tenants that don’t actually qualify as recoverable under the specific lease language, gross-up calculations applied inconsistently between similar tenants, reconciliation statements issued late enough to strain tenant relationships and invite scrutiny, and a lack of documentation trail when a tenant disputes a charge — which turns a routine question into a drawn-out negotiation. Many of these mirror the broader CAM reconciliation challenges property teams face day-to-day. For investors, the stakes are simply higher, because the impact of each one rolls up to portfolio-level returns rather than staying isolated to a single tenant relationship.
How Investors Can Improve CAM Expense Recovery
Three levers tend to matter most:
- Standardize expense categorization so recoverable costs — maintenance, insurance, utilities, management fees — aren’t missed, misclassified as non-recoverable, or coded inconsistently from one accounting period to the next.
- Centralize lease-specific terms like caps, exclusions, gross-up methods, and base years, so they’re applied consistently across every reconciliation instead of re-interpreted from the lease document each cycle, which is where manual error tends to creep in.
- Review reconciliation history at acquisition and annually thereafter, rather than only when a tenant dispute forces the question. A property that hasn’t been reconciled carefully for several years rarely reveals that fact on its own. It takes a deliberate review to surface it.
Together, these three changes shift CAM reconciliation from a reactive, year-end task into a consistent input you can actually rely on for NOI forecasting and portfolio benchmarking.
When Should Investors Consider Outsourcing CAM Reconciliation?
Outsourcing tends to make sense when portfolio size outpaces internal team bandwidth, when reconciliation quality needs to be standardized across recently acquired properties, or when diligence-grade documentation is needed on a timeline internal teams can’t absorb alongside other year-end work. Springbord supports real estate investors with CAM reconciliation services built specifically to protect NOI, backed by 9+ years of CAM reconciliation, lease administration, and real estate accounting experience, ISO-certified process quality, and a track record of 60K+ CAM reconciliations handled for property owners, REITs, and asset managers.
FAQ: CAM Reconciliation for Real Estate Investors
How often should investors review CAM reconciliation accuracy across a portfolio? Investors should review CAM reconciliation accuracy at least annually and conduct an additional review during acquisition due diligence or when recurring recovery variances appear. The review should examine expense classification, lease-specific recovery rules, allocations, caps, gross-ups, and supporting documentation.
What documents should investors request to verify CAM reconciliation history before buying a property? At minimum: the last 2–3 years of reconciliation statements, the underlying expense ledgers they were built from, any tenant dispute correspondence, and documentation of how caps, exclusions, and gross-ups were applied. Gaps or inconsistencies in this paper trail are often more telling than the numbers themselves.
How can investors spot CAM revenue leakage before it shows up in NOI? Leakage is usually visible earlier than the NOI impact if you compare recovery rates and expense categorization across similar tenants or similar properties in a portfolio — a tenant or asset that consistently recovers less than comparable ones is often the first sign, well before the gap is large enough to move the reported NOI.
When does outsourcing CAM reconciliation make sense for real estate investors? It depends on scale and internal bandwidth. Outsourcing tends to add the most value when a portfolio has grown faster than internal reconciliation capacity, or when diligence-grade documentation is needed across recently acquired properties.
What should investors look for when choosing a CAM reconciliation partner for a multi-property portfolio? Look for experience across multiple lease structures and property types, a consistent methodology applied uniformly across every asset, clear audit-ready documentation, and the capacity to onboard newly acquired properties quickly without disrupting reconciliation timelines on the rest of the portfolio.
How does CAM reconciliation affect NOI for commercial real estate investors? Accurate CAM reconciliation can improve NOI by ensuring that recoverable operating expenses are billed and collected according to lease terms. Under-recovered expenses can reduce NOI, while incorrect or overly aggressive charges can create disputes and collection issues.
Why should investors review CAM reconciliation during acquisition due diligence? CAM reconciliation history can help investors identify unrecovered expenses, inconsistent expense classifications, tenant disputes, and recurring recovery gaps that may affect sustainable NOI. Reviewing this history can also reveal opportunities to improve expense recovery after acquisition.